CIBIL Score Ranges Explained: What Is a Good Credit Score ?
If you’ve ever applied for a loan or a credit card in India, you’ve probably heard the term “CIBIL score” thrown around like it holds the key to your financial future. And honestly, it kind of does. Whether you’re planning to buy a house, book a new bike, or simply want a credit card with better rewards, your CIBIL score plays a bigger role than most people realise.
But here’s the thing — a lot of people know they have a CIBIL score without really understanding what the number means. Is 650 good? Is 750 excellent? What happens if your score drops below 600? Let’s break it all down in plain language, so by the end of this article, you’ll know exactly where you stand and what to do about it.
What Exactly Is a CIBIL Score?
CIBIL stands for Credit Information Bureau (India) Limited, and it’s one of the four credit bureaus authorised by the Reserve Bank of India to track and report your credit history. Your CIBIL score is a three-digit number ranging from 300 to 900 that summarises how reliably you’ve handled credit in the past — things like loan repayments, credit card bills, and overall debt management.
Lenders use this number as a quick snapshot of your creditworthiness. A higher score signals that you’re a low-risk borrower, while a lower score suggests there might be some red flags in your repayment history.
The CIBIL Score Ranges Explained
Let’s get straight to the numbers, since that’s probably why you’re here.
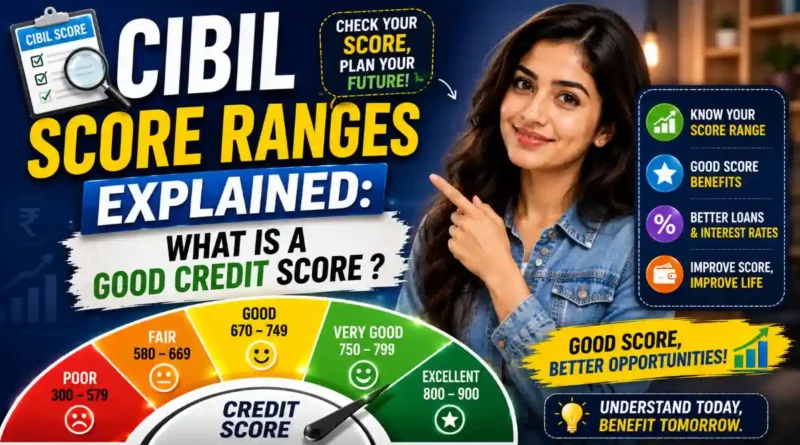
300–549: Poor
This is the lowest bracket, and if your score falls here, getting a loan or credit card approved will be genuinely difficult. Most lenders view this range as high risk, and even if you do get approved, expect steep interest rates and stricter terms.
550–649: Fair
Scores in this range aren’t disqualifying, but they’re not doing you any favours either. You might get approved for smaller loans or secured credit cards, but premium products and the best interest rates will likely stay out of reach.
650–749: Good
This is where things start looking up. A score in this range tells lenders you’re a reasonably responsible borrower. You’ll have access to a wider range of loan products, and interest rates will be noticeably more competitive than in the fair range.
750–900: Excellent
This is the sweet spot. If your CIBIL score sits at 750 or above, you’re in the best possible position. Banks and NBFCs will compete for your business, offering lower interest rates, higher loan amounts, faster approvals, and premium credit cards with better perks.
Most financial institutions in 2026 consider anything above 750 as a strong indicator of financial discipline, so if that’s where you are, give yourself a pat on the back.
What’s Considered a “Good” Credit Score in 2026?
While the ranges above give a general framework, lending criteria has tightened slightly in recent years as banks rely more heavily on data-driven risk assessment. In 2026, most lenders consider 750 and above the benchmark for a genuinely “good” score, with anything above 800 putting you in an elite category that unlocks the best possible loan terms.
That said, a score of 700–749 is still workable. You won’t get rejected outright, but you might not get the lowest interest rates on offer. If you’re sitting in this bracket and have a big purchase coming up — a home loan, for instance — it might be worth spending a few months improving your score before you apply.
Why Your CIBIL Score Range Matters More Than You Think
It’s easy to assume a credit score only matters when you’re applying for a loan, but its influence goes further than that.
Interest rates depend heavily on your score. Even a difference of 50 points can change your home loan interest rate by a noticeable margin, which over a 20-year tenure adds up to lakhs of rupees in extra interest.
Credit card approvals and limits are tied to it too. A higher score often means a higher credit limit right from the start, along with access to premium cards that come with cashback, travel benefits, and lounge access.
Some employers check it during hiring. This is more common in finance-related roles, but it’s a reminder that your credit score can quietly follow you into unexpected areas of life.
Landlords and insurers sometimes factor it in. While this isn’t universal, some rental agreements and insurance premiums are influenced by your credit history in certain cities.
What Factors Affect Your CIBIL Score?
Understanding the ranges is only half the picture — knowing what moves the needle is just as important.
- Payment history (35%) — This is the single biggest factor. Late payments, missed EMIs, or credit card defaults hurt your score significantly, and the damage can take months to repair.
- Credit utilisation ratio (30%) — This refers to how much of your available credit limit you’re actually using. Keeping utilisation below 30% is generally recommended.
- Length of credit history (15%) — A longer track record of responsible credit use works in your favour, which is why closing your oldest credit card isn’t always a good idea.
- Credit mix (10%) — Having a healthy combination of secured loans (like a home loan) and unsecured credit (like credit cards) shows lenders you can manage different types of debt.
- New credit inquiries (10%) — Applying for multiple loans or cards in a short span can make you look credit-hungry, which may lower your score temporarily.
How to Improve Your CIBIL Score
If your score isn’t quite where you’d like it to be, the good news is that it’s entirely possible to improve it with consistent effort.
- Pay your bills on time, every time. Set up auto-pay if you tend to forget due dates — this single habit has the biggest impact on your score.
- Keep credit card usage low. Try not to max out your limit, even if you plan to pay it off in full each month.
- Avoid applying for too much credit at once. Space out your applications rather than applying for several cards or loans within the same month.
- Check your credit report regularly. Errors do happen, and disputing inaccurate entries can sometimes give your score an instant boost.
- Don’t close old credit accounts unnecessarily. A longer credit history generally works in your favour, so think twice before shutting down that old card.
Conclusion
Your CIBIL score isn’t just a number — it’s a reflection of your financial habits, and it directly affects the kind of financial opportunities available to you. Understanding where you fall on the 300–900 scale, and what that range means practically, puts you in a much stronger position when it’s time to apply for credit.
If you’re not sure where you currently stand, it’s worth checking your CIBIL score today. Many banks and financial platforms now offer free score checks, and knowing your number is the first step toward improving it. Whether you’re aiming to cross into the “good” range or push further into “excellent,” small, consistent financial habits will get you there.